Subscribe to outperform
The weekly Executive Briefing: insights, books, tools, and media opportunities worth your attention — curated and distilled into 5 minutes.



The GCC is home to some of the world’s highest concentrations of young, tech-savvy, and financially aspirational consumers. Smartphone penetration is among the highest globally, and demand for mobile-first financial services has never been greater. Yet, despite this digital readiness, there remains a gap between consumer expectations for instant digital experiences and the way financing is traditionally delivered.
FLOOSS Group was founded to close that gap. Founded by Chairman and Founder Tariq AlSaffar and led by CEO and Co-Founder Fawaz Ghazal, FLOOSS launched in Bahrain in 2023 with a single premise: that credit decisions taking days should take minutes. Today, the company delivers instant, Sharia-compliant cash loans and buy now pay later products through a mobile app, backed by its own financing license in Bahrain, a license secured in Saudi Arabia in 2025, and operations being established in the UAE. Embedded finance forms part of the company’s long-term growth strategy and product roadmap.
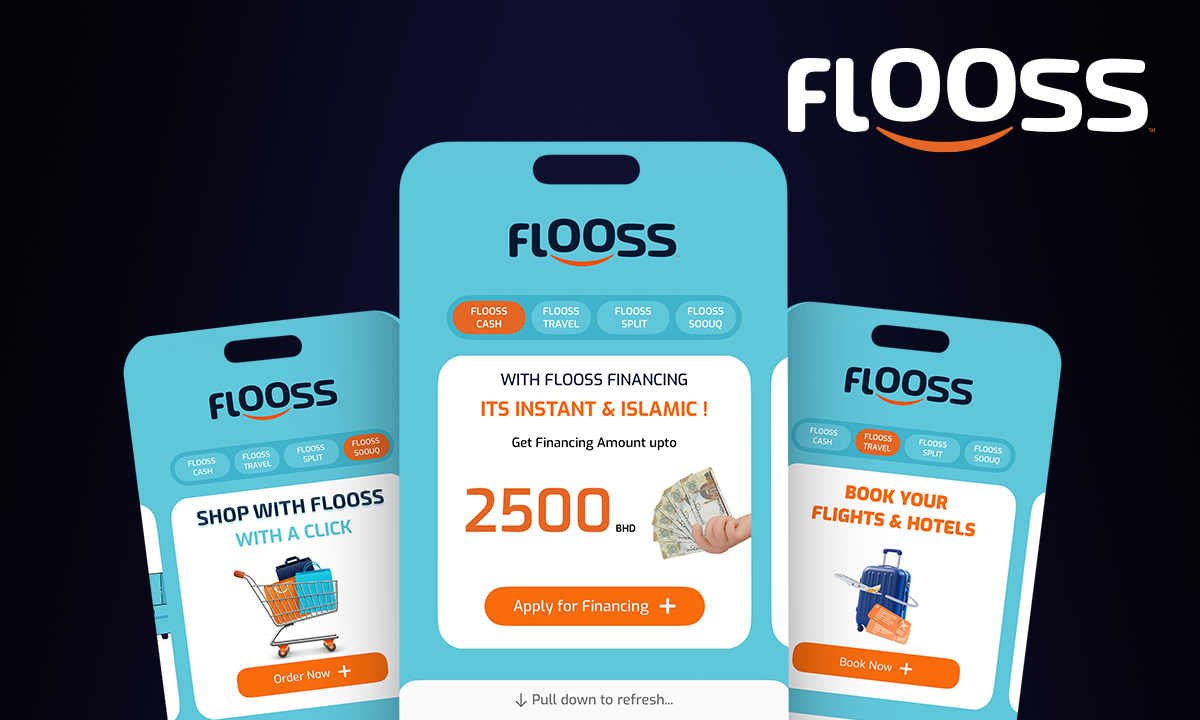
FLOOSS delivers instant, Sharia-compliant financing, backed by its own licenses in Bahrain and Saudi Arabia.
The distinction Ghazal insists on is this: FLOOSS is not trying to be a bank. “We want to be that brand that is empowering customers, helping customers to solve their financial needs instantly,” he says. “Not just as a lending company, but as a company that provides the empowerment of your financial needs.” The point is less about product category than about the emotional register of the transaction: making the moment of financial need less frightening rather than more bureaucratic.
The mechanics run on proprietary technology FLOOSS owns outright. Credit scoring models draw on conventional government-provided digital data—e-KYC records, open banking feeds, credit bureau information—that GCC governments have made available as part of broader digitization efforts, and non-financial data the company captures about the consumer. Those streams feed AI and machine learning models that FLOOSS continuously retunes to raise acceptance rates while keeping default rates down. The product suite covers cash loans, a Sharia-compliant BNPL product, and Souq, a marketplace for electronics, furniture, and appliances on installment plans. Education financing—school fees, professional courses—is in development, not yet live.
What sets FLOOSS apart is how deeply it owns its technology. The full stack is built and maintained by an in-house engineering team running on two-week release cycles, with AI agents assisting development and A/B testing baked into the product process. The credit assessment engine is continuously retrained as data accumulates, enabling FLOOSS to refine its decision-making models, improve customer outcomes, and accelerate product development as it scales. This proprietary platform is the foundation of FLOOSS’s broader embedded finance vision across the GCC.
For Ghazal, responsible lending is not just a regulatory obligation; it is a guiding principle. FLOOSS is designed to provide consumers with access to regulated, transparent, and responsible financing solutions at the moments they need them most. “We want lending to be responsible lending,” Ghazal explains. “We want to help customers take loans on needs rather than wants.” That philosophy is embedded in the product design itself, from the sectors FLOOSS targets (education, healthcare, essential purchases) to the credit limits and repayment structures it offers.
The strategic sequencing is deliberate. Bahrain served as the regulatory sandbox: small enough to iterate quickly, advanced enough digitally to generate the clean data that credit models actually need. Saudi Arabia and the UAE represent the commercial prize: two of the largest consumer markets in the Arab world, with young demographics and governments building the digital infrastructure FLOOSS’s model depends on. Oman, Qatar, and Egypt are on the horizon, framed by Ghazal as regulatory-dependent, not guaranteed. Geographic expansion, in his telling, is not a function of ambition; it is a function of what each jurisdiction’s data environment will actually support.
As each new market opens, FLOOSS arrives with a platform already proven at scale: its technology refined in Bahrain, its credit models sharpened on real consumer data, and its product suite expanding into travel, insurance, and education financing. The ambition is not simply to lend money, but to become the region’s go-to brand for instant, responsible financial empowerment. “We’re still at the beginning of the journey. Our focus is to continue expanding our products, our technology, and our regional footprint while making financing more accessible to consumers across the GCC.”
Learn more about FLOOSS at Flooss.
Hiring your first employee is the point at which a self-employed person becomes an employer, and almost everyone gets the arithmetic wrong in the same direction. They budget the salary, confirm the revenue covers it, and make the offer. The salary is not the cost. It is somewhere between two thirds and three quarters of […]
ARKHO is a Chilean tech startup that has become one of Latin America's most formidable AWS partners.
As companies race to adopt AI and data tools, Alessandro Vergendo argues the science only delivers when people, science and technology work as one system. A company can now measure almost everything about its business except the one thing most likely to break it: the people running it. Alessandro Vergendo built VEGA Consultancies L.L.C. in […]
A sleep schedule rarely breaks all at once. A deadline keeps you up until one, a flight lands late, the weekend runs long, and by Monday your body wants to sleep at 2am and wake at ten while your calendar starts at eight. Here is […]
Most consulting rates are set by guessing. Someone asks what you charge, you name a number that feels brave but not ridiculous, and that number quietly decides your income for the next two years. There is a better way. Work out what your year has […]
Most personal development books get read once, enjoyed and forgotten by the following quarter. A few are worth a second read, because they change what you do on an ordinary Monday rather than how you feel on a Sunday afternoon. The ten below pass that […]
You ask an AI for a statistic and it hands you one, with a footnote. You click the footnote and the number is not on the page. That is where the Perplexity vs ChatGPT choice really begins. Perplexity is built to find sources and put […]
The first meeting usually goes pleasantly. The office is warm, the adviser is good company, and by the end you have talked about your children, your plans for retirement and the house you might sell one day. What you have rarely done is ask the […]
You have two offers on the table, or two candidates, or two ways to spend the next year, and you have been going round in circles for a week. What you are looking for is a decision making framework, something that turns the loop into […]
The first week of the holiday goes well. You sleep ten hours a night, read a novel for the first time in a year, and start to feel like yourself. Then, somewhere around the Sunday before you fly home, the dread comes back. Two weeks […]
Most advice on how to manage stress at work treats stress as a personal failing: breathe better, sleep more, download an app. Those help at the edges. They leave untouched the thing that makes work stressful for most people, which is having a lot asked […]
Most people asking how to become a consultant already have the hard part: years of doing something well inside a company. What they lack is a way to sell it. Consulting is a business built on a narrow promise, and the people who struggle usually […]
Is an online MBA worth it? For a working professional who wants the knowledge and the credential without giving up a salary, it can be one of the better deals in higher education. For someone who wants to change careers, it is often the weaker […]
The weekly Executive Briefing: insights, books, tools, and media opportunities worth your attention — curated and distilled into 5 minutes.

Welcome to The Executive Insight. Your free AI guide to the best tools is on its way. The first issue arrives soon. Check your promotions tab if it is not in your inbox!
Your request has been successfully submitted. Please wait for a reply from our manager, he will contact you as soon as possible.
Your copy of The Executive Insight Book Challenge List is downloading now. Enjoy the list — and while you're here, take a look at our latest interviews.