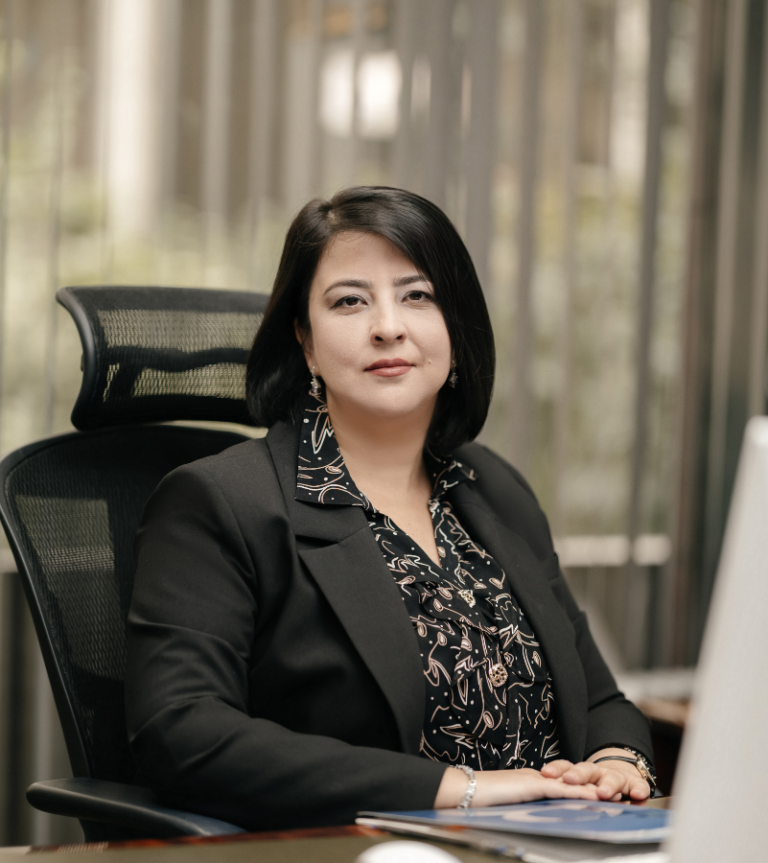
"Financial inclusion and a premium experience rarely coexist in the same institution. We set out to prove they can."

What have been the key factors behind International Bank of Tajikistan’s growth and success?

In 2014, the banking sector here was dominated by institutions that had been around for decades. Cash remained the dominant way people managed their finances. Digital banking was something you read about happening elsewhere. A small group of us sat down and asked a simple question: what if we built something different? A bank designed for the way people actually live today, not the way they lived thirty years ago.

That question became IBT. From the start, we knew we could not compete on legacy or branch count. The vision was straightforward: put technology and trust at the center, grow faster than the market, and never take reckless risks to do it.

That strategy proved to be the right one. In 2025, we posted strong asset growth and became one of Tajikistan’s largest banks by assets. But I do not mention these results to impress. They reflect something real: customers are choosing a bank that makes their lives measurably easier.

IBT24 became the foundation of that. It is not a digital channel attached to a traditional bank — it is the bank itself. Customers transfer money by phone number, pay bills, and manage their finances without ever visiting a branch. In a country where cash dominated until recently, making digital transactions a daily habit changes everything.

Through Visa Direct Account, our customers send money directly to bank accounts abroad. In a country where remittances sent home by relatives working abroad have historically played an important role in the economy, this is essential infrastructure. Our Moody’s B3 rating with stable outlook and annual independent external audits give independent proof that stability is more than a promise.

Behind every service is a team. None of this would work without the people who build it — engineers, risk managers, customer support teams who challenge themselves every day to make banking simpler and more accessible. They are the real story behind the numbers.

Today, less than ten years later, IBT has grown into one of the country’s recognized financial institutions. We still have a lot to improve. Every growing bank does. But the direction is clear.

What are the bank’s core business areas and primary financial products and services today?

IBT serves three groups: retail customers, small and medium enterprises, and corporate clients. The logic is the same across all three — to cover the full financial life of our customers within a single ecosystem.

Retail is where our identity was shaped. IBT24 lets people transfer money, pay bills, and see every transaction in real time. The card range runs from the national “Korti Milli” card to Visa Platinum, Visa Infinite with complimentary DragonPass airport lounge access, and premium Mastercard. Cardholders also receive further premium benefits, including enhanced travel insurance, Fast Track services, yQ Meet & Assist services at airports, and other exclusive privileges. It is a deliberate choice to cover the full spectrum — from someone opening their first card to a frequent traveler who expects global benefits.

We were among the first in Tajikistan to introduce Visa and UPI card tokenization for Android. Instant card issuance is available across all branches. And the Visa credit card we launched — called “Insof,” meaning “conscience” in Tajik — reflects our approach to responsible lending. These are not just milestones. Each solved a real problem: security for mobile payments, convenience for customers who should not have to wait, and fair access to credit.

International transfers are a responsibility, not just a product line. Visa Direct Account enables direct transfers to bank accounts abroad. More broadly, IBT24 is built around leading international payment systems, including Visa, Mastercard, and UnionPay, so customers can send money directly to bank accounts abroad rather than relying on cash pickup services. For families depending on money from relatives overseas, getting this right matters beyond revenue.

For businesses, we offer merchant acquiring, cash management, and lending to entrepreneurs. Businesses outside the main cities face the same geographic limits as households, so these tools run through the same IBT24 platform rather than requiring in-person account management. The goal is an ecosystem where customers handle daily finances inside a single app — whether they are an individual in Dushanbe or a growing business in Khujand.

How does the International Bank of Tajikistan differentiate itself in Tajikistan’s competitive banking sector, and what are its key strengths?

Every major bank in Tajikistan has its own history. Some rely on state networks. Others focus on specific customer groups. Our path has been different: technology combined with an international standard of service. The competition is on the quality of the digital experience, not on branch count.

Three things set us apart, and I believe they are genuinely hard to replicate.

First, “International” is not just our name — it is built into how we operate. Products are designed for customers whose lives cross borders: direct overseas transfers, premium cards with global benefits, audits and credit ratings to international standards. Relationships with Visa, Mastercard, and UPI are grounded in real compliance — AML, KYC, security protocols — not partnership announcements.

Second, speed comes from not having legacy baggage. As a newer institution, there are no decades-old systems to work around. That means faster updates, quicker feature launches, and the ability to respond to what customers actually need. Our above-market growth follows from that agility.

Third, the full range, without compromise. From a basic card with minimal fees to Visa Infinite — the standard of service is consistent. The standard approach in Tajikistan has been to build separate products for mass-market and premium customers. We chose instead to provide additional value to our cardholders through premium benefits. Financial inclusion and a premium experience rarely coexist in the same institution. We set out to prove they can. This customer-focused approach became one of the factors behind our significant asset growth in 2025.

To be honest, we do not claim to be the best at everything. There are strong players with their own advantages. But the focus on being a technology-driven international bank is clear, and the results speak for themselves.

Like any growing bank, we continue learning every day.

How is the bank expanding its presence and contributing to the development of the financial sector in Tajikistan?

When people ask about expansion, they usually expect to hear about new branches. That is not our answer.

Tajikistan has about 11 million people, spread across terrain that is 93% mountainous, which limits how far any branch network can reach. The bank that succeeds here is not the one with the largest real estate footprint. It is the one that goes deepest into how people actually manage their money.

So the focus is on four things, none of them about physical space.

First, the digital ecosystem keeps deepening — IBT24 evolves from a banking app into a broader platform. Second, the shift away from cash continues, and we aim to be the infrastructure behind it: acquiring for businesses, payment tools for consumers, transparent transfer systems. Third, attention goes to segments where loyalty runs deepest — premium banking, SMEs, international transfers. Fourth, every decision is weighed against preserving the ratings, asset quality, and trust people have placed in us.

As for the broader contribution — every secure transaction, every international standard met, every customer brought into the digital economy strengthens the country’s financial infrastructure. Financial inclusion is not a slogan. It is the core of what we do.

Looking ahead, work continues on open APIs, better data-driven credit scoring, and deeper integration with the digital standards Tajikistan is setting.

How does International Bank of Tajikistan build long-term relationships with its retail, corporate, and institutional clients while creating value for its partners?

The philosophy is straightforward: long-term profit follows from genuinely improving people’s lives. That is not a mission statement. It is how the bank operates every day.

Trust comes from transparency. Clear pricing, instant transfers, secure operations — in an environment where trust in banks has historically been fragile, it is earned through specifics. The digital channel reinforces this: when customers see every transaction in real time and control their own money, trust is built into the experience itself.

Tajikistan is 93% mountainous. We do not copy products designed for flat, urban markets. We design for our reality — so a customer in a remote village receives the same quality of service as someone in central Dushanbe. Customers outside the capital have historically had less access to full-service banking because branch networks concentrate in cities. IBT24 lets customers in remote areas transfer money and pay bills without a branch visit, extending our services into areas with limited branch coverage.

What drives the team? I am proudest of something straightforward: we are making modern financial technology ordinary in Tajikistan. When a customer opens IBT24 and it just works — that is success. When someone in a small town uses a card instead of cash for the first time — that is real progress.

With partners, international standards are the language we share. The Moody’s rating, the annual independent external audits — these are not badges on a website. They are how global partners evaluate trust. And they hold us accountable.

Looking forward, our ambition is simple: to build a bank that the next generation of Tajikistan will be proud to call its own. We believe the future of banking here will be digital, transparent and international — and we intend to help shape that future.

Latest From The Executive Insight

  • Wealth

    The offer email arrives. The number is fine, maybe slightly less than you hoped, and the recruiter is waiting for an answer. Most people say yes. Knowing how to negotiate salary at this exact point is worth more than at any other moment in the […]
    8 min read
  • Mindset

    The busiest office workers are interrupted every two minutes during core hours. That figure comes from Microsoft’s own data on how people use its software, and anyone who runs a team will recognise it. Most productivity hacks are written for a calendar you control. The […]
    8 min read
  • Wellness

    The alarm goes off at six. You hit snooze twice, get up at half past, and spend the first hour of the day feeling like someone else is driving. Most advice on how to become a morning person starts with the alarm: set it earlier […]
    9 min read
  • Business

    A project lands that your team cannot carry. The product launch is in four months, the two engineers you need do not exist on your payroll, and a permanent hire will take most of that time just to find. Staff augmentation is the usual answer: […]
    10 min read
  • Lifestyle

    Most people meet Alex Hormozi through a video clip: a muscular man in a T-shirt explaining, with some impatience, why your business is not making money. The books are better than the clips. Alex Hormozi books are short, blunt manuals on three problems every business […]
    9 min read
  • Editorial

    Most of the decisions that shape a company are made on an ordinary afternoon, between two other meetings, by someone who is slightly tired. Decision making in business mostly happens in small moments: a yes sent from a phone, a hire approved because the role […]
    9 min read
  • Education

    It is a Sunday evening and you are dreading the morning again. Not the workload, which you can handle, but the sameness of it. You have been good at this job for fifteen years and you can picture the next fifteen with no surprises in […]
    9 min read
  • Wealth

    The email from HR arrives on a Friday afternoon. Your last day is in three weeks, and in the attachment there is a line about what happens to your 401k. Within a day, somebody in your network has suggested an advisor who can “help with […]
    9 min read
  • Mindset

    The biggest client calls at nine on a Monday to say they are leaving. By ten, two things need to happen. Someone has to work out what the lost revenue does to payroll, which projects pause and who tells the team what. And someone has […]
    11 min read
  • Wellness

    You open a document to write one paragraph. Four minutes later you are reading an email you did not need to read, with two new tabs open and the paragraph unwritten. If that sounds like most of your working day, you are in good company, […]

    8 min read